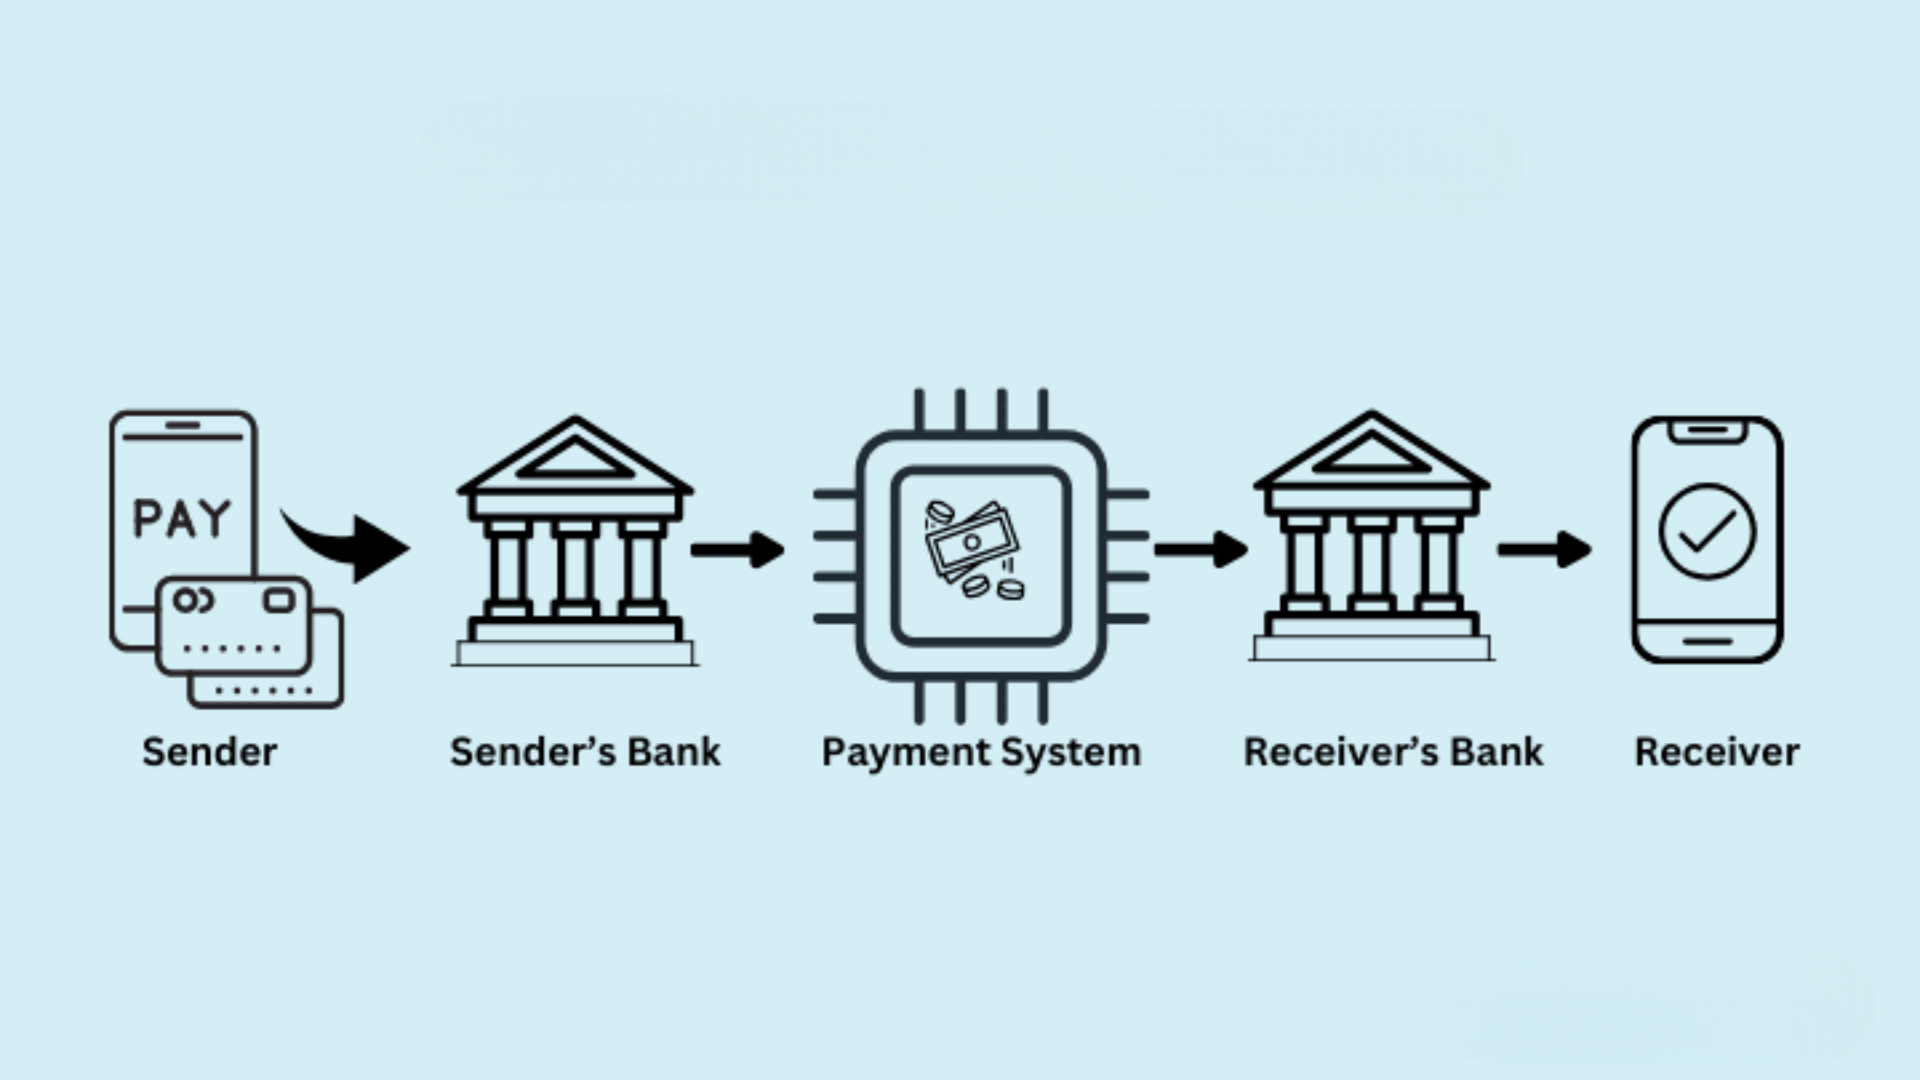
Bank transfers are the invisible plumbing of the global economy. Whether you are splitting a dinner bill with a friend, paying a supplier overseas, or receiving a salary, the movement of money between accounts happens with a speed and reliability that most users take for granted. Yet behind every transaction lies a complex orchestration of messaging protocols, clearing systems, and settlement mechanisms. This article breaks down how bank transfers work from the inside out, covering the key participants, the lifecycle of a transfer, the major networks involved, and the security layers that protect your funds.
The Core Participants in a Bank Transfer
A bank transfer is never a single action. It is a coordinated exchange involving multiple parties. Understanding these roles is essential to grasping why transfers behave the way they do.
- Originator: The person or entity sending the money.
- Originating Bank: The institution where the sender holds their account. It validates and debits the funds.
- Beneficiary: The recipient of the funds.
- Beneficiary Bank: The institution that credits the recipient’s account.
- Intermediaries: Correspondent banks, clearinghouses, or payment processors that facilitate the transfer when the two banks do not have a direct relationship.
- Regulators and Networks: Bodies such as the Federal Reserve, SWIFT, or regional automated clearing houses that set rules and route messages.
In a domestic transfer, the chain is often short: two banks and a central clearing system. In an international transfer, the chain can expand to include multiple correspondent banks, each taking a cut and adding time.
The Lifecycle of a Bank Transfer
Every bank transfer follows a predictable sequence, though the timing and terminology vary by network. The following stages describe the general flow.
The distinction between clearing and settlement is crucial. Clearing is about information and obligations; settlement is about the final transfer of value. In many modern systems, these steps are compressed into seconds, but the underlying logic remains the same.
Major Bank Transfer Networks
Different networks serve different purposes. The table below summarizes the most common systems used in the United States and internationally.
| Fedwire | Real-time gross settlement | Minutes to hours | High-value, time-critical domestic transfers |
| ACH | Batch clearing | 1–3 business days | Payroll, direct deposits, recurring payments |
| RTP and FedNow | Instant payment | Seconds | Real-time consumer and business payments |
| SWIFT | Messaging network | 1–5 business days | Cross-border transfers and trade finance |
| SEPA | Regional clearing | Same day to next day | Euro-denominated transfers within Europe |
It is worth noting that SWIFT does not move money. It moves standardized messages between banks. The actual settlement occurs through correspondent accounts or local clearing systems. This is why international transfers often involve multiple fees and delays.
The Role of Correspondent Banking
When two banks do not have a direct relationship, they rely on correspondent banks. A correspondent bank holds accounts for other banks and acts as an intermediary. For example, a small bank in one country may use a large global bank to settle transactions in a foreign currency.
This model introduces friction. Each correspondent bank may charge a fee, apply its own compliance checks, and add processing time. It also creates opacity: the sender may not know which intermediaries are involved or how much will be deducted along the way. Fintech companies and newer payment rails are actively working to bypass this model by building direct connections or using blockchain-based settlement.
Security and Compliance Layers
Bank transfers are subject to stringent security and regulatory controls. These protections are designed to prevent fraud, money laundering, and terrorist financing.
- Encryption: Payment messages are encrypted in transit using protocols such as TLS and, in some networks, additional message-level encryption.
- Authentication: Multi-factor authentication, digital signatures, and hardware tokens verify the identity of senders and institutions.
- Fraud Monitoring: Machine learning models analyze transaction patterns in real time to flag anomalies.
- AML and KYC: Banks must verify customer identities and monitor transactions for suspicious activity under anti-money-laundering and know-your-customer rules.
- Sanctions Screening: Every transfer is checked against lists of prohibited individuals and entities.
These layers add latency but are non-negotiable in the current regulatory environment. The challenge for the industry is to maintain security while meeting rising expectations for instant, low-cost transfers.
Why Transfers Sometimes Fail or Get Delayed
Even in a highly automated system, transfers can go wrong. Common causes include incorrect account numbers or routing codes, mismatched beneficiary names, insufficient funds, compliance holds, network outages, and currency cut-off times. Understanding these failure modes helps both consumers and businesses plan better.
For instance, a single typo in an IBAN can cause an international transfer to bounce back after several days, often with fees deducted. Similarly, a transfer initiated after a network’s daily cut-off may not process until the next business day. Real-time payment systems reduce but do not eliminate these issues.
The Future of Bank Transfers
The direction of travel is clear: faster, cheaper, and more transparent. Instant payment schemes are expanding globally. Open banking APIs are allowing third parties to initiate transfers directly. Central bank digital currencies are being piloted in multiple countries. Blockchain-based settlement networks promise near-instant cross-border payments without correspondent banks.
Yet the fundamental principles remain unchanged. A bank transfer is still a message, a validation, a clearing, and a settlement. The technology evolves, but the need for trust, accuracy, and regulatory compliance persists. For technologists and product builders, understanding this stack is essential to designing the next generation of payment experiences.
Mastering the mechanics of bank transfers is not just an academic exercise. It is the foundation for building reliable financial products in an increasingly interconnected world.
Leave a Reply